Antimony Alongside Gold: How Multi-Metal Systems Are Valued
October 7, 2026
When Gold and Interest Rates No Longer Move Together: What It Means
October 7, 2026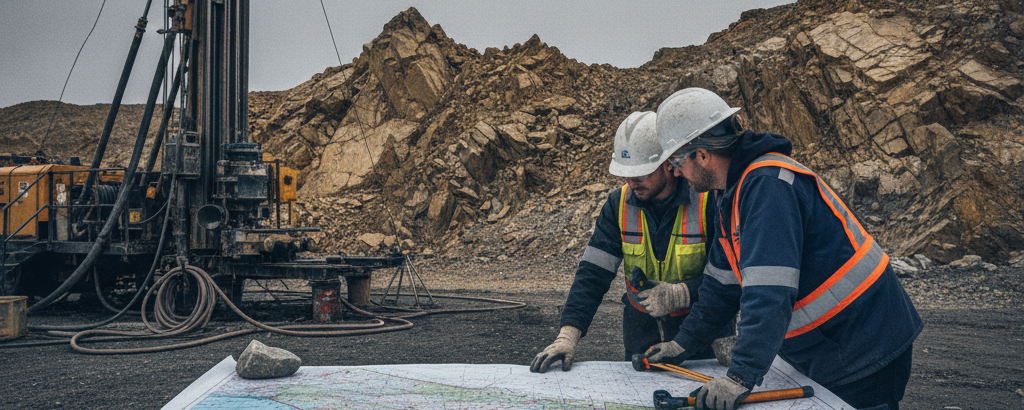
When a major joins the drill program
Large producing companies don’t enter junior exploration deals out of goodwill. By the time a deal is signed, months of internal geological work have already been done. That is why earn-in agreements are worth paying attention to: they show what professionals are prepared to spend on early-stage ground, and on what terms.
The gold sector has seen several such deals lately. Below we explain what drives them, how the model works, and what it means for small-cap investors when a major takes on part of a junior’s exploration risk.
How earn-ins work
An earn-in is neither a corporate acquisition nor a loan. The principle is straightforward: the major commits to investing a defined sum over a set period into the junior’s project, usually through drilling or geological studies. In return, it gradually acquires a growing ownership stake, somewhere between 51% and 70% in most cases. The junior keeps control of its concession area at first but transfers a portion of it as the major hits successive spending milestones.
A rough analogy: it is like someone offering to renovate your house at their own expense and receiving a pre-agreed share of it once a specified investment threshold is reached. Whether that is a good deal depends entirely on how valuable the house turns out to be once the work is done — and that question only gets answered later.
What each side gains, and what each gives up
The earn-in model addresses a persistent problem in the junior sector: small explorers rarely have the means to fully finance expensive drilling programs without hitting shareholders with heavy dilution. At the same time, they often hold geologically promising ground they cannot develop alone.
For the junior, the major absorbs drilling costs up to the earn-in threshold, which protects the balance sheet considerably. Majors also bring in technical teams that have already assessed the project before signing anything. The deal closing sends a signal to the market, though that signal is often overweighted.
For the major, the model works like a call option on early-stage exploration: it pays more only if drilling results justify continued spending, and it avoids buying a company before knowing what it actually has.
The risks run both ways. For the junior, the arrangement can look costly in hindsight if the project turns out to contain a large deposit. In the 1990s, several junior explorers in Nevada sold interests under the prevailing market terms of the day that later became significant mines. Parting with a stake in a half-empty concession feels different from parting with a stake in a proven one.
| Feature | For the Junior | For the Major |
|---|---|---|
| Capital flow | No direct drilling costs | Expenditures replace a purchase price |
| Control | Initially retained, gradually transferred | Grows with each investment milestone |
| Risk | Dilution through stake transfer | Exploration expenditures with no guarantee |
| Signal value | Credibility gain in the market | Strategic pipeline secured at lower cost |
What earn-ins reveal about the gold market
When earn-in deals cluster within a short period, there is usually a reason. The pattern is cyclical: when gold prices are elevated and majors are depleting reserves faster than they replace them, pressure to explore builds. Rather than risk expensive acquisitions at the wrong project stage, companies fill their exploration pipeline through earn-ins instead.
Ontario’s Red Lake district is a concrete example. It has been among Canada’s most active gold addresses for decades, and majors have repeatedly entered agreements with smaller explorers there to consolidate adjacent geological systems.
One technical distinction that gets lost in press coverage: when a major drills under an earn-in and adds material to the resource inventory, those quantities are classified under the NI 43-101 standard as resources (Inferred, Indicated, or Measured), not as reserves (Probable or Proven). The difference matters. Reserves are economically mineable and bankable; resources describe geological occurrence without that certainty. Earn-in phases operate almost entirely within resource classification.
Reading the terms before reading the headline
Earn-in agreements change the risk profile of a junior explorer without removing the risk. Investors following these companies should start by examining the deal terms: what is the maximum stake the major can acquire? Are there milestone stages, so-called tranched earn-ins? Can the junior co-fund its remaining interest afterward, or will it face further dilution? These details appear in the source documents that publicly listed companies in Canada must file with SEDAR+.
The partner itself deserves scrutiny. A globally operating producer with experience in the same geological province adds different value than a counterpart that signed primarily to hold an option.
Time horizon matters too. Earn-ins typically run three to seven years. The project is geologically active during that period, but the junior generates no revenue. Entering at this stage requires patience.
Earn-in announcements frequently trigger short-term price moves in small explorers, sometimes with double-digit gains on the day. Whether that is fundamentally justified depends on the deal terms and the project’s stage. Signal value and economic substance are different things, and keeping that gap in mind is worth the effort.
Earn-in terms at a glance
- Earn-in agreement
- A contract in which one partner (typically a major) acquires a growing ownership interest in a project through defined expenditures, usually exploration costs, without paying an upfront purchase price.
- Major
- A large, producing mining company with stable cash flow, an in-house technical team, and an international presence. Usually publicly listed with a high market capitalization.
- Junior explorer
- A small company in the early exploration or development stage, with no ongoing production. Finances itself primarily through equity raises and partnerships.
- NI 43-101
- The Canadian regulatory standard for public disclosure of mineral resources and reserves. It defines how geological data may be classified and communicated.
- Inferred resource
- The lowest NI 43-101 resource category; based on limited data and carrying high uncertainty. Cannot be used directly in feasibility studies.
- Reserves vs. resources
- Reserves (Proven/Probable) are economically mineable quantities established with high confidence. Resources (Measured/Indicated/Inferred) describe geological occurrence without guaranteeing economic extractability.
- SEDAR+
- Canada’s regulatory filing platform (System for Electronic Document Analysis and Retrieval), where publicly listed companies must publish mandatory documents such as contracts, technical reports, and quarterly disclosures.
- Project consolidation
- A strategy in which adjacent or geologically related concession areas are brought under a single owner or partnership to increase exploration and development efficiency.
⚠️ Important notice: This article is for informational and educational purposes only. It does not constitute investment advice, a recommendation, or a solicitation to buy or sell any security. Investments in small-cap exploration and mining companies carry a high risk, including the potential total loss of capital. Before making any investment decision, consult a registered financial advisor and conduct your own analysis. Boersen Post Team is not responsible for decisions taken based on the content published here.