Carried Interest in Uranium Juniors: How Partner Drilling Works
October 20, 2026
Côte d’Ivoire: Why ASX Junior Miners Are Betting on West Africa
October 22, 2026
When gold projects are cheaper than their own history
Anyone who has spent time studying gold mining history will notice a recurring pattern: waves of takeover activity, then long stretches of quiet, then the cycle repeats. Right now, many publicly listed junior gold developers trade at prices well below what was paid for comparable projects in earlier acquisitions. In some cases, the discount to those historical deal values has exceeded 80 percent.
For anyone new to the sector, that’s a strange idea. Why would a company sitting on a proven gold resource in the ground be worth so little? The answer has to do with the relationship between small exploration companies and the large, production-oriented mining majors — and with how capital flows bend that relationship out of shape.
Capital scarcity and the valley of the juniors
Junior mining companies don’t produce anything. They explore ground, define resources, and push projects far enough along that a larger company steps in — or they attempt the rare jump to production themselves, which rarely works out. Their value depends primarily on two things: the gold price and the availability of risk capital.
When capital dries up — because institutional investors turn cautious or interest rates climb — it exits the least liquid corners of the market first. Juniors, often listed on smaller exchanges like the TSX Venture Exchange in Canada or the ASX in Australia, take the hardest hits. Share prices drop even though the gold sitting in the ground hasn’t changed.
At that point, a junior’s market price no longer reflects the strategic value of its resource. It reflects sentiment. Think of it like residential real estate during a credit squeeze: houses don’t deteriorate, but buyers disappear, so prices fall anyway. The junior gold market works much the same way.
How M&A logic among majors shifts the dynamics
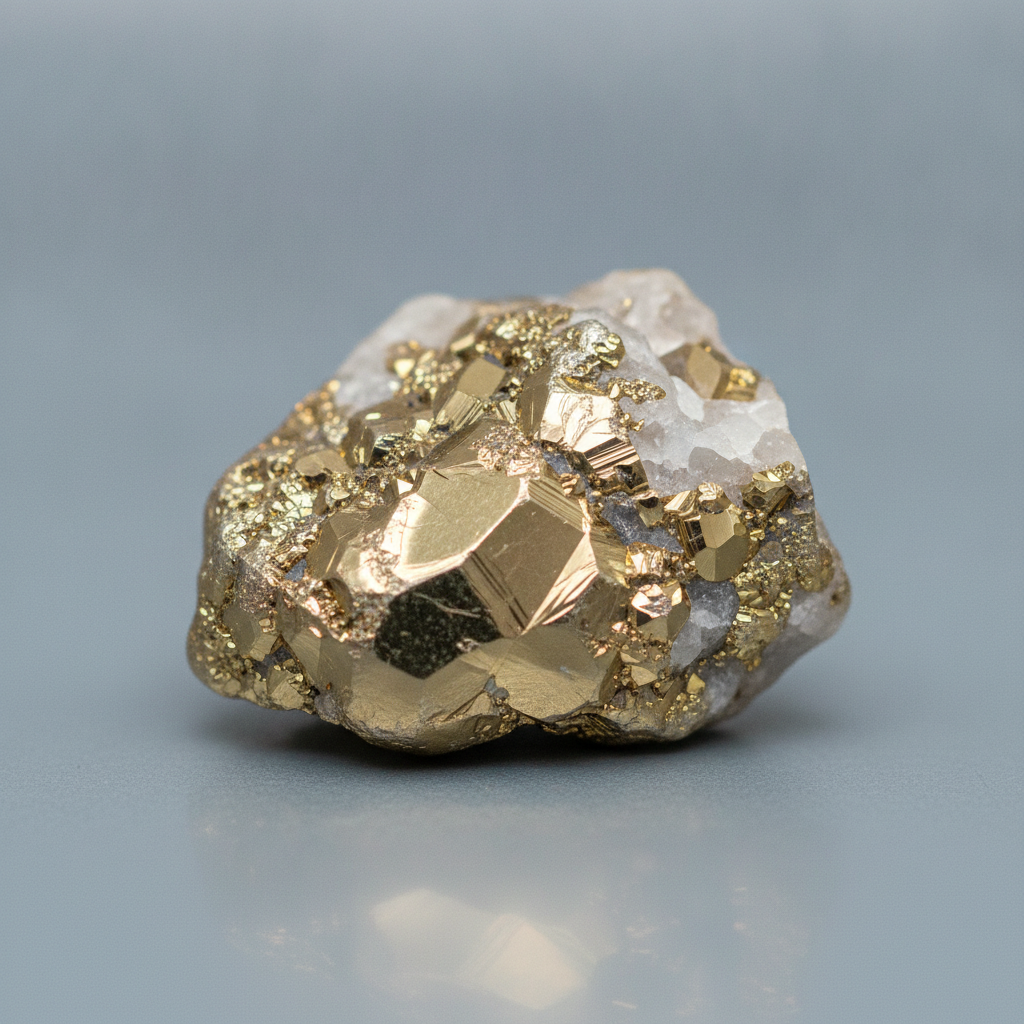
Large gold producers have a concrete problem: existing mines deplete, in-house exploration pipelines rarely keep pace, and new projects take many years to reach production. Acquiring a junior that has already done the expensive exploration work is faster and often cheaper than building from scratch. When juniors trade at compressed valuations, acquisition costs drop accordingly. M&A waves in the gold sector have historically emerged when the gold price holds at elevated levels while junior valuations have not yet caught up — a time lag that was visible in the early 2000s, reappeared after the 2008/09 financial crisis, and showed early signs again after 2016.
A useful comparison: a pharma company with a drug in Phase II trials but no money for Phase III is often bought by a large corporation at a premium to market value but below what in-house development would cost. In the gold sector, the classified resource plays the same role as that not-yet-finished drug — and the same logic determines who ends up buying it.
| Characteristic | Junior with resource | Pure exploration junior |
|---|---|---|
| Resource status | Inferred / Indicated / Measured | No classified resource |
| Acquisition attractiveness | Higher – volume known | Lower – potential unproven |
| Valuation basis | In-situ value of the resource | Exploration potential, geology |
| Typical risk profile | Medium (development risk) | High (discovery risk) |
Reading valuation gaps
Not every discount means the same thing. A company already holding a resource reported under NI 43-101 — the Canadian reporting standard for mineral resources — sits in a different risk category than one pointing only to geological anomalies.
The terminology is tightly regulated. Inferred Resources carry the lowest confidence level, Indicated Resources a medium level, and Measured Resources the highest. None of these categories equals a Reserve, which requires demonstrated economic feasibility. That distinction is easy to miss and expensive to overlook.
When M&A wave discussions come up, they usually concern companies with a solid resource base already in the development stage, not early-stage explorers with no classified tonnage. The number worth tracking is the spread between a company’s current market cap and what a major would realistically need to pay in a deal — because that gap is what creates the acquisition logic in the first place.
A discount alone, though, doesn’t trigger a takeover. Majors need the right combination of strategic pressure, available capital, and market conditions before they move. Anyone watching this segment should track not only project quality but also the balance sheet strength of the large producers and what their management is saying about reserve replacement.
Terms worth knowing before entering the sector
- Junior developer
- A small mining company that has already defined a mineral deposit through drilling and is in the development stage — meaning it is not yet producing, but holds a classified resource.
- M&A (mergers and acquisitions)
- In the mining sector, M&A typically refers to the acquisition of a smaller explorer or developer by a large producer seeking to expand its resource base.
- Inferred / Indicated / Measured Resources
- Categories of resource estimation under international standards (e.g., NI 43-101). They describe the confidence level of the estimate: from low for Inferred to high for Measured. None of these categories equates to a Reserve.
- Reserve vs. resource
- A resource describes the quantity of a mineral that has been inferred or confirmed to exist in the ground. A reserve is only the portion whose economic extraction is considered feasible under current conditions — a significantly stricter criterion.
- Valuation gap
- The difference between a company’s current market value and the price a strategic acquirer would be willing to pay in a takeover. In the junior gold sector, this gap typically arises from capital scarcity and investor sentiment, not from any deterioration of the resource itself.
- In-situ value
- The calculated value of a mineral still in the ground, based on quantity, grade, and the current metal price — before deducting mining, processing, and capital costs. It is a reference figure, not a market value.
- TSX Venture Exchange (TSXV)
- A Canadian stock exchange for smaller growth companies, particularly in the commodities sector. Many junior mining companies are listed there and exhibit lower liquidity than on major exchanges.
⚠️ Important notice: This article is for informational and educational purposes only. It does not constitute investment advice, a recommendation, or a solicitation to buy or sell any security. Investments in small-cap exploration and mining companies carry a high risk, including the potential total loss of capital. Before making any investment decision, consult a registered financial advisor and conduct your own analysis. Boersen Post Team is not responsible for decisions taken based on the content published here.