Phased Drilling Programs: How Lithium Juniors Build Resources
August 13, 2026
Start Investing: A Beginner’s Complete Guide
August 13, 2026
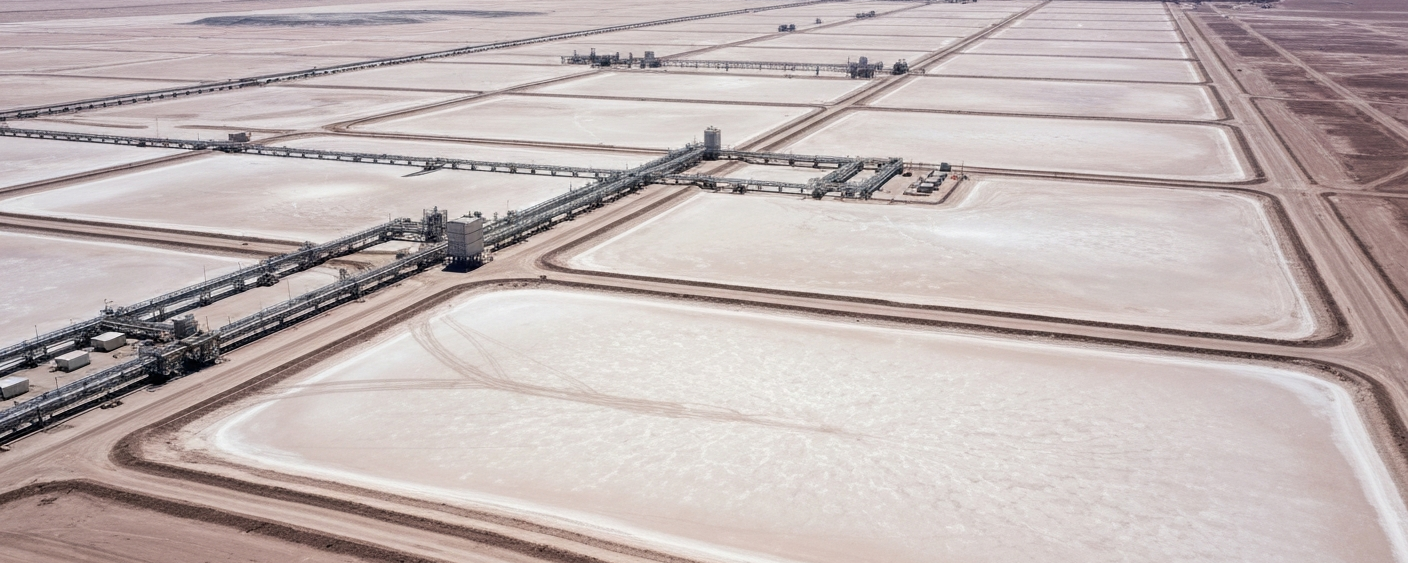
When a state giant knocks on a junior explorer’s door
The scene repeats itself across commodity cycles: a small exploration company drills quietly for years in a remote desert, accumulates data, reports results, and waits. Then a strategic buyer appears and the junior’s valuation jumps. For a long time, that buyer was usually a Western major — Rio Tinto, Glencore, one of the familiar names. More often now, it is a state-controlled mining company from an emerging market, working to a timeline and with objectives that most Western investors find unfamiliar.
Understanding why these buyers behave the way they do is worth the attention of anyone holding small-cap mining positions.
Resource security as a political mandate
The calculation behind state-owned mining companies targeting junior explorers is not complicated. Whoever controls the raw materials of the energy transition controls a meaningful share of their country’s industrial future. Lithium sits near the center of this, as a key input for lithium-ion batteries used in electric vehicles and stationary storage systems.
Countries such as India, China, and Brazil have been running active resource security strategies for years. Their state-owned enterprises are mandated to prevent supply bottlenecks — not primarily through market mechanisms but through direct stakes and outright acquisitions. The difference from a private buyer matters: a state-owned enterprise rarely acts on pure return logic. Supply security and geopolitical positioning are at least equally important, and sometimes dominant.
The practical consequence is that state buyers will often pay premiums a return-driven investor would walk away from. For junior explorers still in resource definition or feasibility work, this can produce a sharp revaluation that has nothing to do with any change in the geology.
Why project stage determines the premium
A mining project moves through defined phases: initial geochemical sampling, resource definition under NI 43-101 or JORC standards, feasibility study, production decision. The earlier a buyer enters, the cheaper the acquisition — and the higher the geological and permitting risk they absorb.
A state-owned enterprise with a 30-year supply horizon can carry that risk more comfortably than a fund manager who needs to justify quarterly performance. Think of a municipal housing developer buying a plot on the city’s outskirts before the road connections are built, versus a private investor who waits for the zoning approval before committing. Same plot, very different calculus. The analogy has an obvious limit: in mining, geology cannot be rezoned, and no amount of strategic patience fixes a resource that turns out to be smaller or lower-grade than expected.
Once it becomes known that a state buyer has expressed interest in a lithium project in a stable jurisdiction — parts of South America, Australia, or Canada — market perception shifts. The question is no longer only “How large is the resource?” but also “Who wants it, and how urgently?”
| Buyer type | Primary objective | Time horizon | Valuation logic |
|---|---|---|---|
| Private mining major | Return on capital | 5–15 years | DCF, cost of capital |
| Strategic industrial buyer (e.g., battery manufacturer) | Raw material security for production | 10–20 years | Production costs, supply guarantee |
| State-owned mining enterprise | National supply security | 20–40 years | Geopolitical value, strategic premium |
Reading the risks, not just the premium
The acquisition premium is the obvious attraction: when a state-owned enterprise buys into a project, it typically pays well above the last quoted market price. Premiums in mining takeovers vary widely depending on project stage and competitive pressure, but they can be large enough to matter enormously for investors holding a position before the announcement.
The risks get less attention. These acquisitions are rarely predictable, and geopolitical objections — regulatory hurdles in the target country or in third countries — can kill a deal after it has already moved the share price. A state buyer’s interest also does not validate the project’s geology. Plenty of projects attract strategic attention and still disappoint technically.
India’s KABIL (Khanij Bidesh India Ltd.) is a useful example. It has acquired stakes in lithium projects in Argentina and Australia in recent years, but local permitting processes and geological uncertainties extended timelines well beyond initial expectations. State capital does not make a project simpler to develop.
The underlying driver — resource security as a political priority — appears durable as long as battery raw material demand grows and governments push to diversify supply chains. For investors, recognizing the pattern helps explain why certain projects attract attention. It does not make outcomes predictable.
Where state policy meets private markets
Junior explorers, traditionally financed through private placements and retail-driven speculation, are being pulled into a geopolitical contest for raw materials that was, until recently, mostly conducted between large national champions. The boundary between state resource policy and private capital markets has shifted in ways that now affect project valuations directly, and which commodities receive policy-driven “critical mineral” designation, with state interest following quickly.
For anyone new to small-cap mining: project fundamentals still matter. Resource size, grades, infrastructure proximity, development costs — none of that disappears. But geopolitical context is a real variable now, not background noise. Some projects get attention their geology alone would not explain, and the reasons for that are worth understanding before a deal announcement rather than after.
Key terms
- State-owned enterprise (SOE)
- A company majority-owned by a government or government body. SOEs operate according to strategic objectives that go beyond profit maximization.
- Acquisition premium
- The markup a buyer pays above a company’s current market price. In early-stage mining takeovers, this premium can be especially high when strategic interests are involved.
- Resource vs. reserve (NI 43-101 / JORC)
- A mineral resource is a geologically estimated quantity of minerals (Inferred, Indicated, Measured). A reserve is the economically extractable portion of that resource (Proven, Probable). The terms signal different levels of project maturity and are not interchangeable.
- Resource security
- The strategic goal of a country or company to ensure long-term supply of critical raw materials, pursued through direct investment, equity stakes, or bilateral agreements.
- Due diligence
- The systematic review of a company or project before a transaction, covering technical, legal, financial, and environmental aspects. State buyers conduct these reviews and still make mistakes.
- Project stage
- The development status of a mining project, running from exploration through resource definition and feasibility studies to a production decision. Earlier stages carry more risk but cost less to acquire.
- Geopolitical resource competition
- The effort by states and state-controlled companies to secure access to strategically important raw materials such as lithium or cobalt, often in direct competition with other nations.
⚠️ Important notice: This article is for informational and educational purposes only. It does not constitute investment advice, a recommendation, or a solicitation to buy or sell any security. Investments in small-cap exploration and mining companies carry a high risk, including the potential total loss of capital. Before making any investment decision, consult a registered financial advisor and conduct your own analysis. Boersen Post Team is not responsible for decisions taken based on the content published here.