Polymetallic Projects: How Copper, Nickel, and Cobalt Create Value Together
August 16, 2026
Africa as a Copper Frontier: Opportunities and Risks for Junior Explorers
August 16, 2026
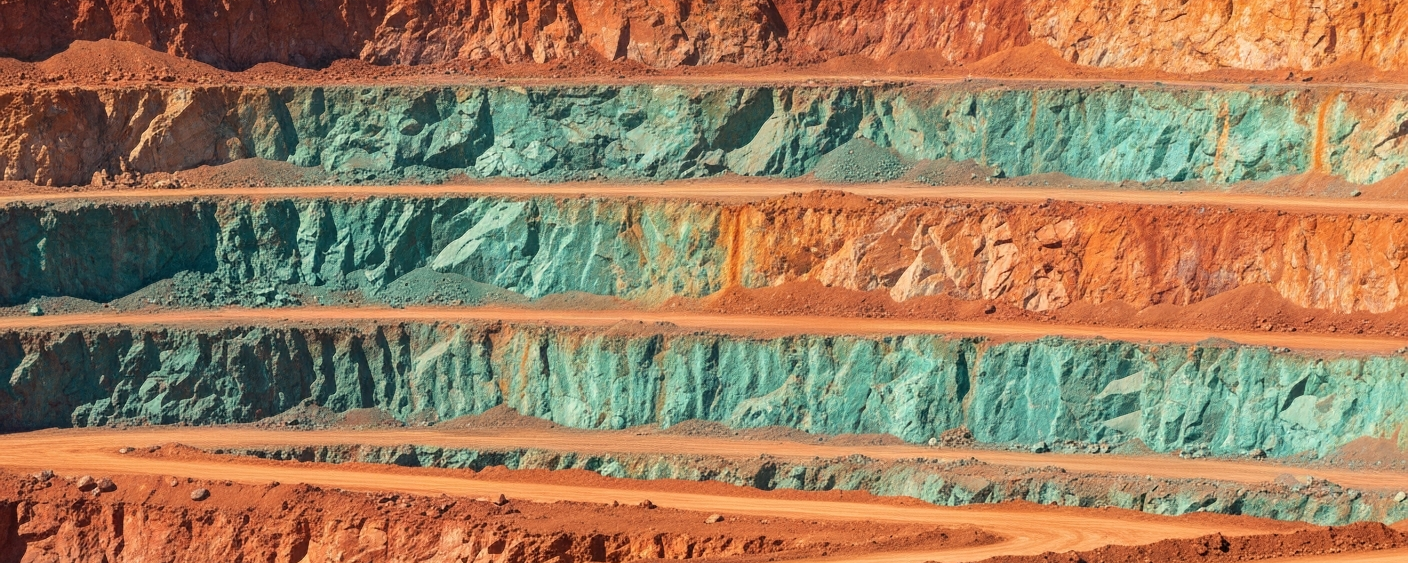
Two metals, one strategy: why hybrid models emerge in exploration
Junior explorers face a familiar problem: capital is scarce and most projects fail before a single drill hole is collared. A small mining company that wants to stay solvent has to manage its money carefully, which means thinking about structure, not just geology. One model that has gained traction is the hybrid project generator.
The concept combines two approaches that have traditionally been kept separate: exploring a primary commodity like copper while simultaneously advancing a gold portfolio, which moves on different markets and attracts different partners. What does this actually mean for how a junior explorer is structured, and why would anyone bother?
Project generators, earn-ins, and partner drilling
A classic project generator acquires or generates exploration properties, does enough early-stage geological work to validate them, then transfers them to larger partners in exchange for a stake. The partner takes on the expensive drilling. The originating company keeps a retained interest and can run multiple projects at once without funding all the drilling itself.
The hybrid project generator adds a second layer: the company holds projects in two structurally distinct metal categories. Copper and gold often occur together geologically — porphyry deposits being the obvious example — but they trade on different markets and are driven by different demand. Copper benefits from energy transition spending and infrastructure buildout. Gold moves on inflation and economic anxiety. These are not the same cycle, which is the whole point.

How risk-sharing works, and where it breaks down
What makes the hybrid model workable for small companies is partner-funded drilling. A larger mining company, typically a mid-tier producer or major, covers drilling costs for a specific project under an earn-in agreement. Once it meets a defined expenditure threshold, it earns a project interest. The junior keeps its equity intact and can direct its own cash toward the gold side while the partner drills copper.
When a recognized operator is willing to spend millions on one of your projects, it also sends a signal to the capital markets. That signal is not a guarantee of anything, but it is real information. And the equity preservation matters: self-funded drilling at comparable scale would require repeated placements that dilute existing shareholders.
The catch is control. An earn-in partner has its own priorities. If the copper price drops or the partner’s internal strategy shifts, the drilling program can slow or stop, and the junior has no real lever to pull. Losing pace on a project because your partner has reassigned its budget is the central operational risk of this model.
| Feature | Classic Explorer | Hybrid Project Generator |
|---|---|---|
| Number of commodities | 1 (focused) | 2+ (diversified) |
| Drilling financing | Equity / placements | Partner-funded + own capital |
| Capital requirements | High (fully self-funded) | Reduced through partner |
| Loss of control | Low | Possible on partner projects |
| Market exposure | 1 metal cycle | 2 independent cycles |
What the model means for the small-cap capital market
Hybrid project generators tend to be less volatile than focused single-metal explorers, but they are also harder to value. Assessing one requires looking at two metal markets, multiple project stages, and several partner relationships at once.
A focused gold explorer is comparatively straightforward to analyze: you look at the resource, the gold price, and management. A hybrid company requires something closer to a portfolio analysis inside a single stock. That raises the information burden, and most institutional investors avoid that kind of complexity. The result is a persistent valuation discount relative to focused peers.
That discount can work in a patient investor’s favor, though. If a company makes progress on both sides of its portfolio, both valuation components can move before the market has caught up. Re-ratings typically happen only when a specific event forces one component into view: a drill result or an earn-in milestone, say, rather than any gradual recognition of underlying value.
What investors should specifically examine with this model
The hybrid model is not inherently safer than any other approach. It only functions as genuine diversification if the projects really do draw on different demand sources and if management can handle multiple partner relationships at once. For a small company with a lean team, that is a concrete operational challenge.
Anyone looking at this type of junior explorer should check how binding the earn-in agreements actually are, and whether the company has enough cash to cover its own share of drilling obligations. The stage of each project also matters: early-stage target generation and resource-defined properties require fundamentally different valuation approaches and carry different risk profiles. The model itself settles none of that.
Key terms at a glance
- Project Generator
- A business model in which a company generates exploration properties and transfers them to partners, typically in exchange for a retained interest. The company does not bear all drilling costs itself.
- Earn-in Agreement
- A contractual arrangement in which a partner acquires the right to earn a project interest by making defined expenditures, usually drilling costs, within a specified timeframe.
- Partner-Funded Drilling
- A drilling program fully or predominantly financed by an external partner. This reduces the capital outflow for the junior explorer but also reduces the company’s control over the pace of work.
- Porphyry Deposit
- A geological deposit type formed by magmatic intrusions, typically containing disseminated copper and/or gold mineralization. Often large in volume but with comparatively low grades.
- Retained Interest
- The ownership stake that the original project holder keeps after an earn-in. It allows participation in project success without additional capital investment.
- Sum-of-the-Parts Valuation
- A valuation method in which different company segments or projects are each valued individually and then added together. Particularly relevant for hybrid models, but also prone to error in early exploration stages.
- Complexity Discount (Valuation Discount)
- A market phenomenon in which complex, difficult-to-assess corporate structures trade at a lower price than focused, more easily valued peers.
- Resource vs. Reserve (NI 43-101)
- Under the Canadian standard NI 43-101, Resources (Inferred, Indicated, Measured) refer to geologically estimated quantities without an assessment of economic viability. Reserves (Proven, Probable) are economically extractable quantities confirmed through a feasibility study. The two terms are not interchangeable.
⚠️ Important notice: This article is for informational and educational purposes only. It does not constitute investment advice, a recommendation, or a solicitation to buy or sell any security. Investments in small-cap exploration and mining companies carry a high risk, including the potential total loss of capital. Before making any investment decision, consult a registered financial advisor and conduct your own analysis. Boersen Post Team is not responsible for decisions taken based on the content published here.